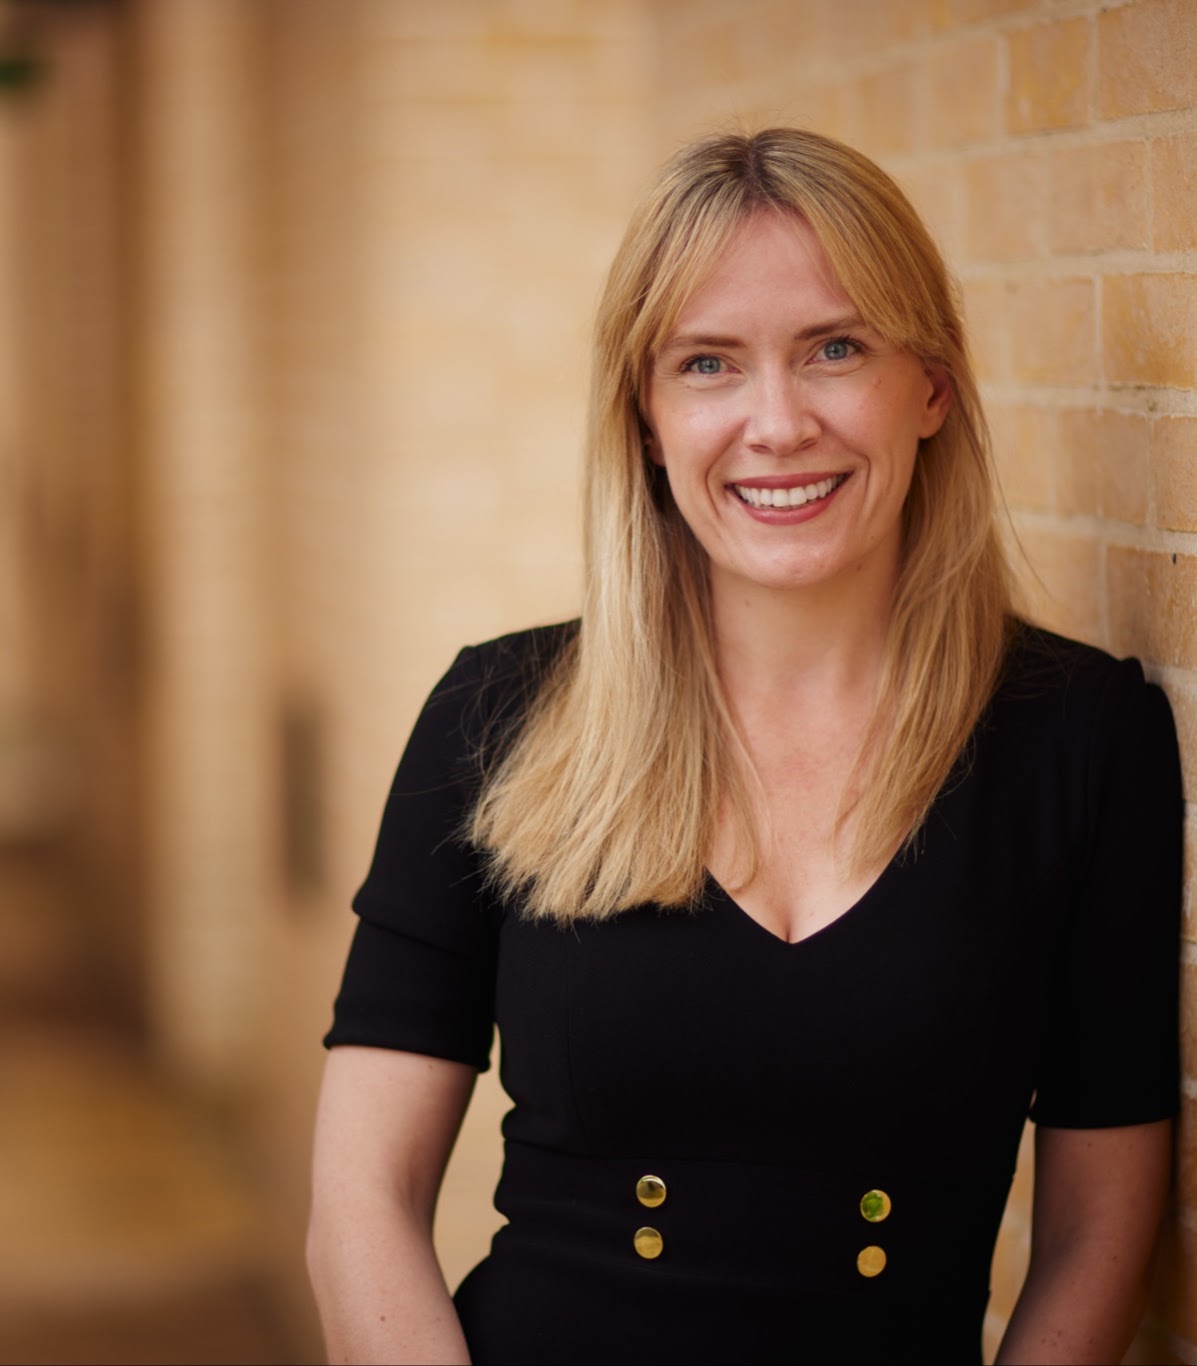
Neroli Austin
Assistant Professor of Finance
Ross School of Business, University of Michigan
Research areas:
- Private Markets
- Real Estate
- Law and Finance
Background:
- A.P. at Ross, 2023–present
- PhD in Finance, University of Oxford, 2023
- Economist, Reserve Bank of New Zealand, 2013–2016
- Bachelor of Laws with First Class Honors and
Bachelor of Economics, University of Sydney, 2013
Working Papers
-
Land Banking and Housing Supply
·SSRNWe study the financing of the U.S. builder sector, and document a new type of shadow banking, which affects housing supply. Bank lending against land collapsed in 2008 and has not returned at its old scale. Instead, builders rely on “land banks,” firms that hold land on their balance sheet and sell land options to builders. We document this new regime in new hand-collected data: The share of land that builders hold via option has grown from 23% in 2009 to 72% in 2025, equivalent to five years of builders’ homebuilding, or above $600 billion at current new-home prices. Builders exercise almost all land options when they come due. Thus, land banks provide balance sheet space, but carry little land price risk in normal times. However, in a land price crash, losses fall on land banks, which are financed with private capital. Based on these facts, we develop a model of the new U.S. housing supply curve. Due to land banking, housing supply is scheduled years in advance, and is about two thirds less price elastic in the short run. This “sticky housing supply” from land banking resulted in roughly 245,000 fewer homes built during the 2020–2021 housing boom, a quarter of annual U.S. single-family homebuilding. We conclude that land banking has contributed to the current U.S. housing shortage.
-
Keeping Up with the Blackstones: Institutional Investors and Neighbors’ Home Investment
Previously circulated as (2023) “Keeping Up with the Blackstones: Institutional Investors and Gentrification”
·SSRNI study the effect of private equity housing investments on the owner-occupiers around them, proposing a novel channel of investor coordination. Consistent with this coordination channel, I find that: (i) After national news converges on a narrative that institutional investment results in higher prices, a one standard deviation increase in recognizable institutional ownership raises owner-occupiers’ home investments by 3.6%. (ii) Anonymous institutional ownership produces no response. (iii) Around recognizable institutions, the effect grows with the number of surrounding owners. (iv) The induced owner-occupier investment is value-preserving maintenance. The induced investment amounts to $1.3 to $1.6 billion per year.
- Heterogeneous Creditors and Cov-Lite Loans
-
Catching a Break: VCs and the Commercialization of Innovation
Draft available upon request
Publications
-
Decomposing Value Gains – The Case of the Best Leveraged Buyout Ever
Teaching
-
Ross School of Business, University of Michigan
- Real Estate Finance
- Real Estate Capital Markets
- Real Estate Finance and Investment
- Real Estate Finance and Investment I
-
University of Oxford
- Head Tutor, Oxford Private Markets Investments Programme
- Head Tutor, Oxford Future of Real Estate Investment Programme
- Teaching Assistant, FinTech
- Teaching Assistant, Big Data